Man buys second house at 24 after saving up £1,000 a month since he was 18

A young man has added a second home to his property portfolio at just 24-years-old after cleverly stashing away money since being 18.
Jacob Waddington, 24, has always put away at least 50 per cent of his wages since leaving college, allowing him to purchase a £98,000 two bed house at age 23.
Now alongside girlfriend Holly, he has been able to splurge on a second property.
He had spent a year doing up the first house before getting it valued at £160,000, and then renting it out. The couple then remortgaged the property and used the equity to purchase a second £140,000 cottage at auction and plans to turn this into an Airbnb.
Advert
Jacob from Lancashire explained: “The plan is to maybe buy one more house to do up and sell, and then maybe buy a doer-upper to live in.
“All my friends and family say it’s amazing, and it does feel really rewarding. I’ve found a real passion for doing it and I just feel really motivated to keep going.”
After leaving college, aged 18, Jacob started working for a Telecoms company, earning £24,000 a year. It was quite the jump from a £6-an-hour retail job so he was able to save a large chunk of his wage.
As Jacob was still living at home and was paying just £200 a month to his parents, he was able to put £1,000 a month into a savings account. His wages then went up to £33,000, meaning he was able to put away around £1,500 out of his £2,200 monthly salary.
“I’d only really spend money on going out at the weekend, but you don’t need to spend loads on that”, he said. “Me and my girlfriend would go for the odd meal out, but we love going on walks and things like that”.
In May 2025, Jacob and Holly discussed what they should use their savings for.
“We thought about buying a house together, but neither of us were desperate to move out, so we decided to buy a house to do up and then sell”, Jacob said.
Couple rented out first home for more than double the mortgage
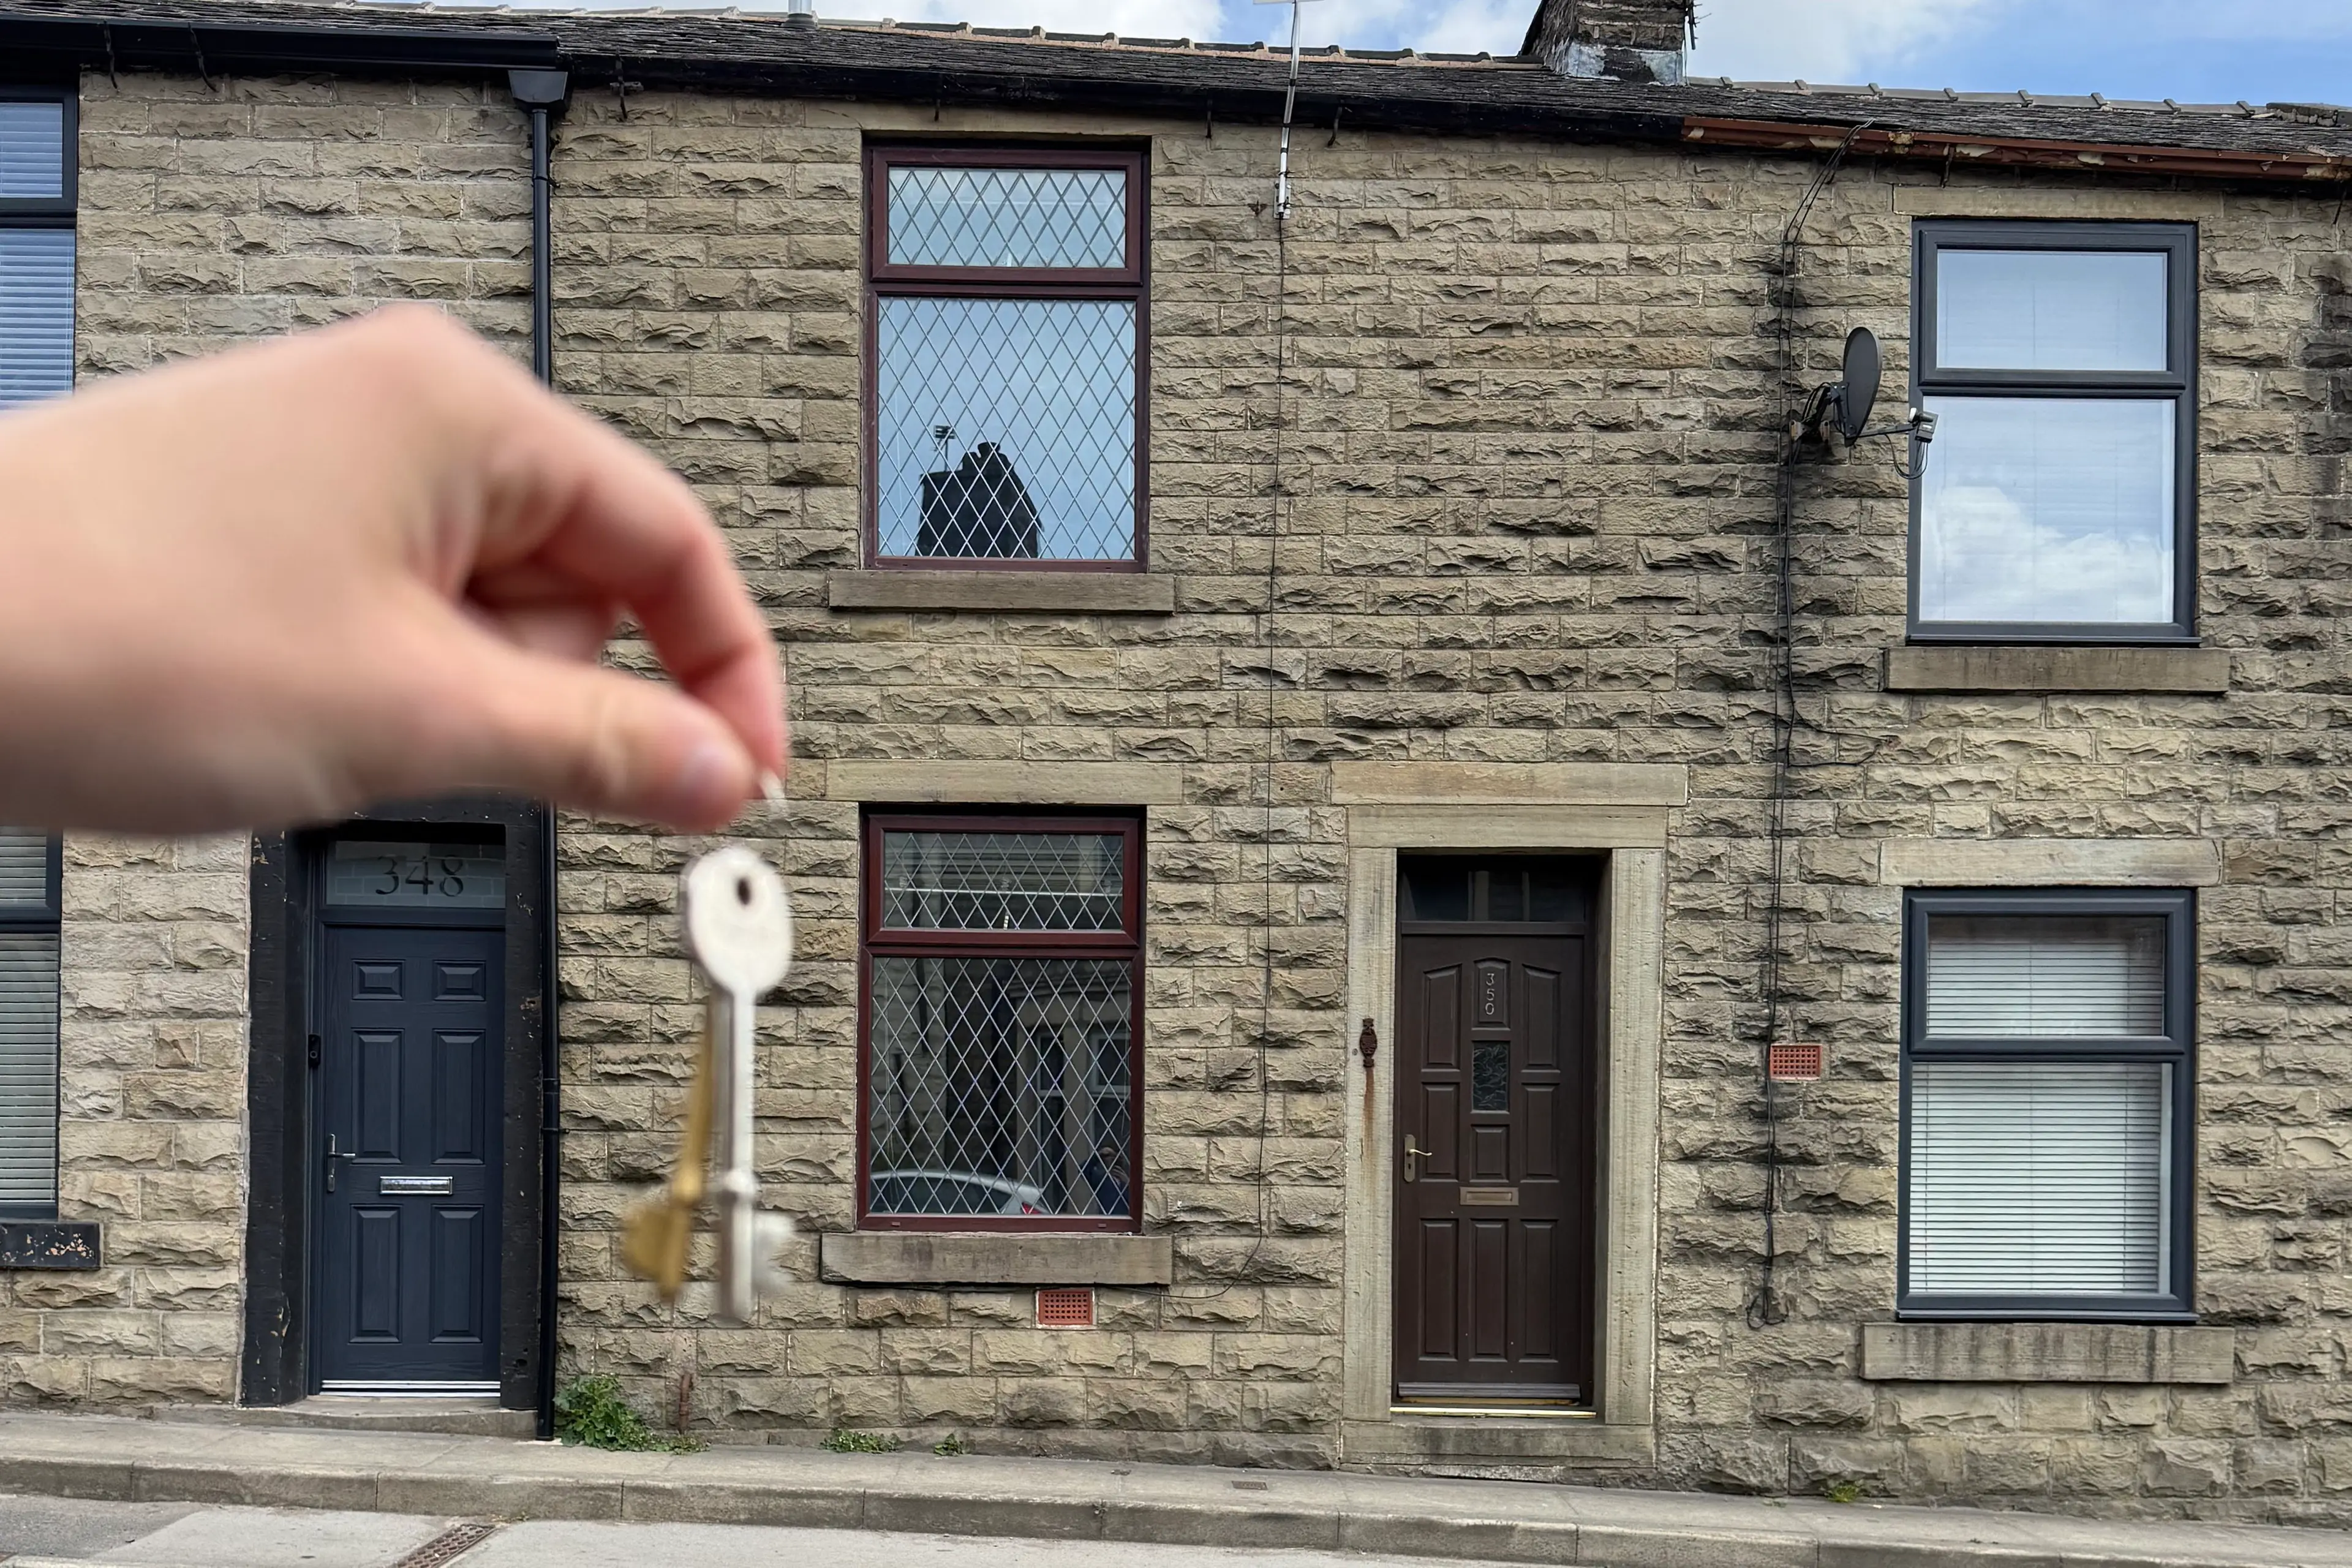
Together they put down a 25 percent deposit on a £98,000 two-bed terraced house and spent £20,000 on renovations. Jacob left his job to work in a bar two days a week, earning £800 a month, and focused the rest of his time on the renovation project.
They put in a new kitchen, a new bathroom, re-plastered the walls, and installed a new boiler. By January 2026, nine months after they purchased the property, the renovation was complete.
They then got the property valued again at £160,000 and withdrew the increase in value to their bank accounts by remortgaging the house.
But instead of selling it, they decided to instead rent it out due to demand in the area. Tenants moved in back in March, paying £875 a month - more than double Jacob and Holly’s £430 a month mortgage.
They then began looking for a second property and found a 200-year-old one-bedroom cottage at the foot of Pendle Hill, in Lancashire, famous for the Pendle witch trials.
“We’re thinking we might Airbnb this one out because it’s in a rural location”, Jacob said. “It’s really picturesque and it’s in a historic area. It will be like a couple’s getaway.”
They used the money made from remortgaging their first property to put towards the £140,000 cottage and took out a 75 percent bridging loan for 12 months on the rest of the property.
A bridging loan is a short-term loan where instead of paying monthly payments, you build up interest over a set period of time.
"Don't be afraid to buy something that needs a little work"
Jacob and Holly plan to spend a year doing up the property and estimate they will spend £30,000 on renovations. They will then get it remortgaged, and use the money made from this to pay off the bridging loan, before moving on to a regular mortgage.
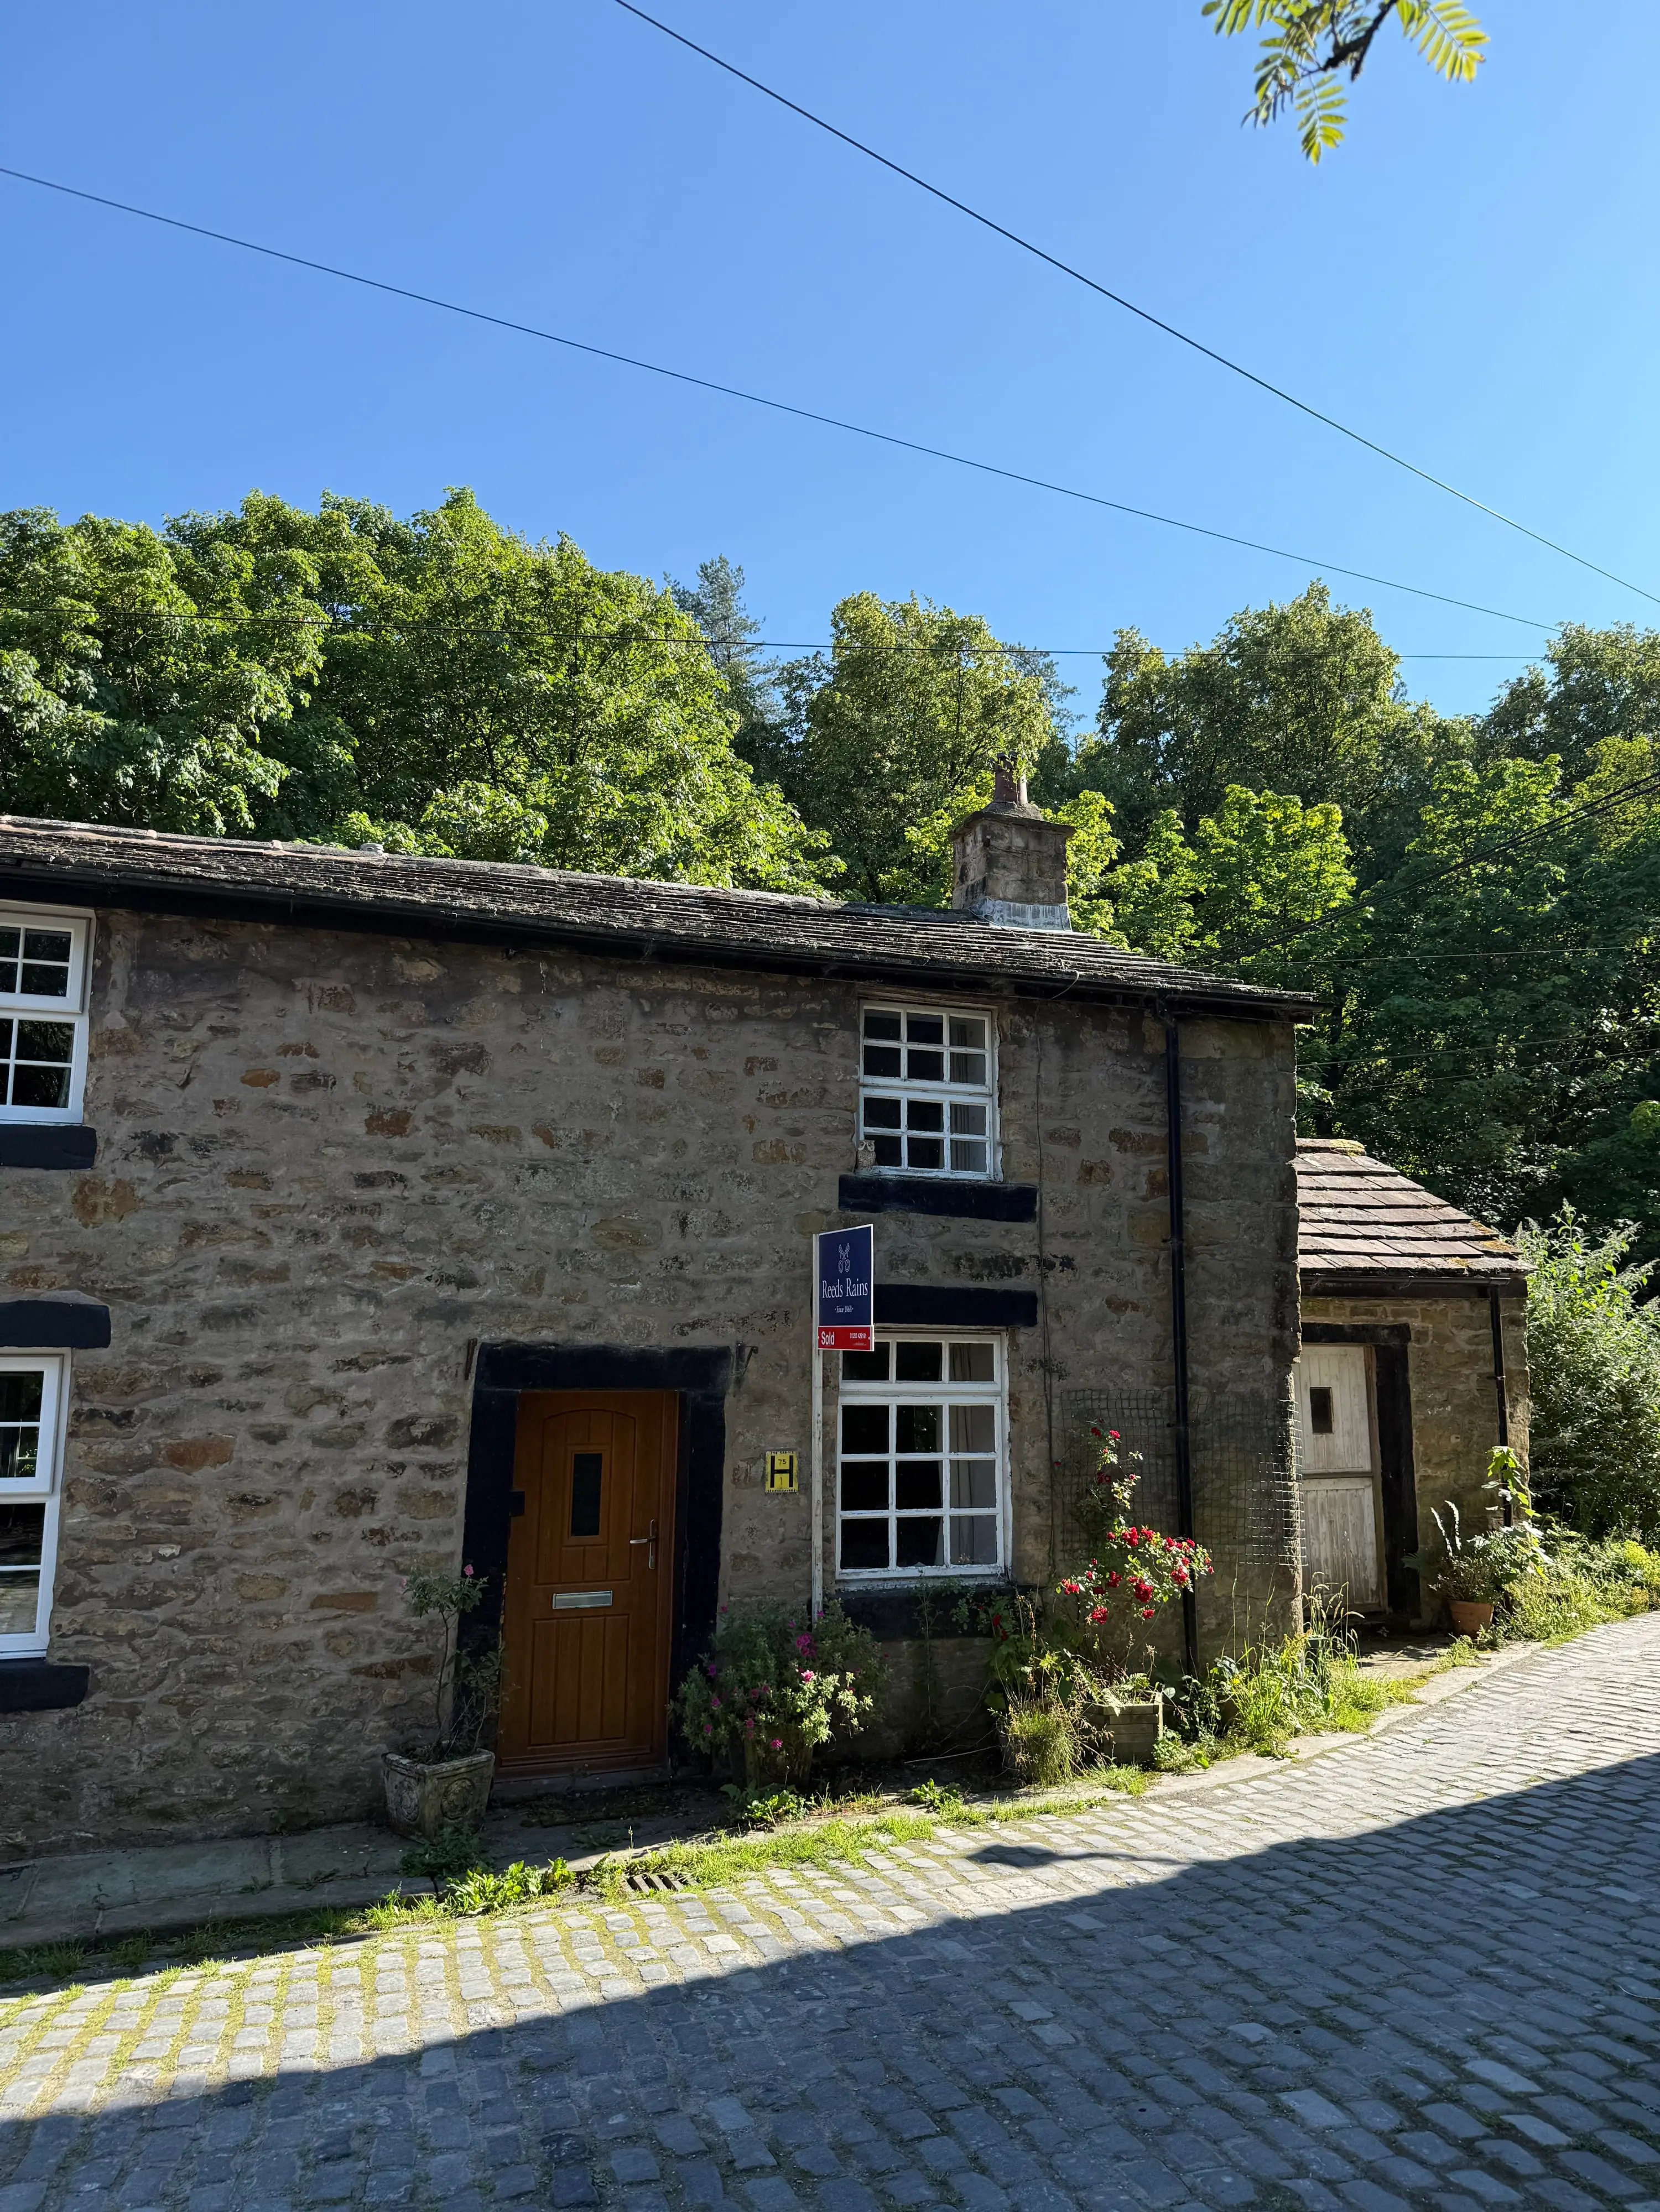
“The house next door has just sold for £320,000 for a two bed, so I’m hoping to get this one remortgaged at around £250,000”, he said.
“If we can do that, we’d be able to pull out more money than we put in, because it will have increased in value by so much”.
Jacob has calculated that if he rents the Airbnb out at £120 a night at a 60 percent occupancy, he will make £2,000 a month. After paying council tax, bills and the £650 mortgage, he will then have around £1,000 leftover.
“It could be more profitable than the standard rental”, he said.
Jacob plans to buy another property to sell our rent out after this one, before purchasing a home to live in with Holly.
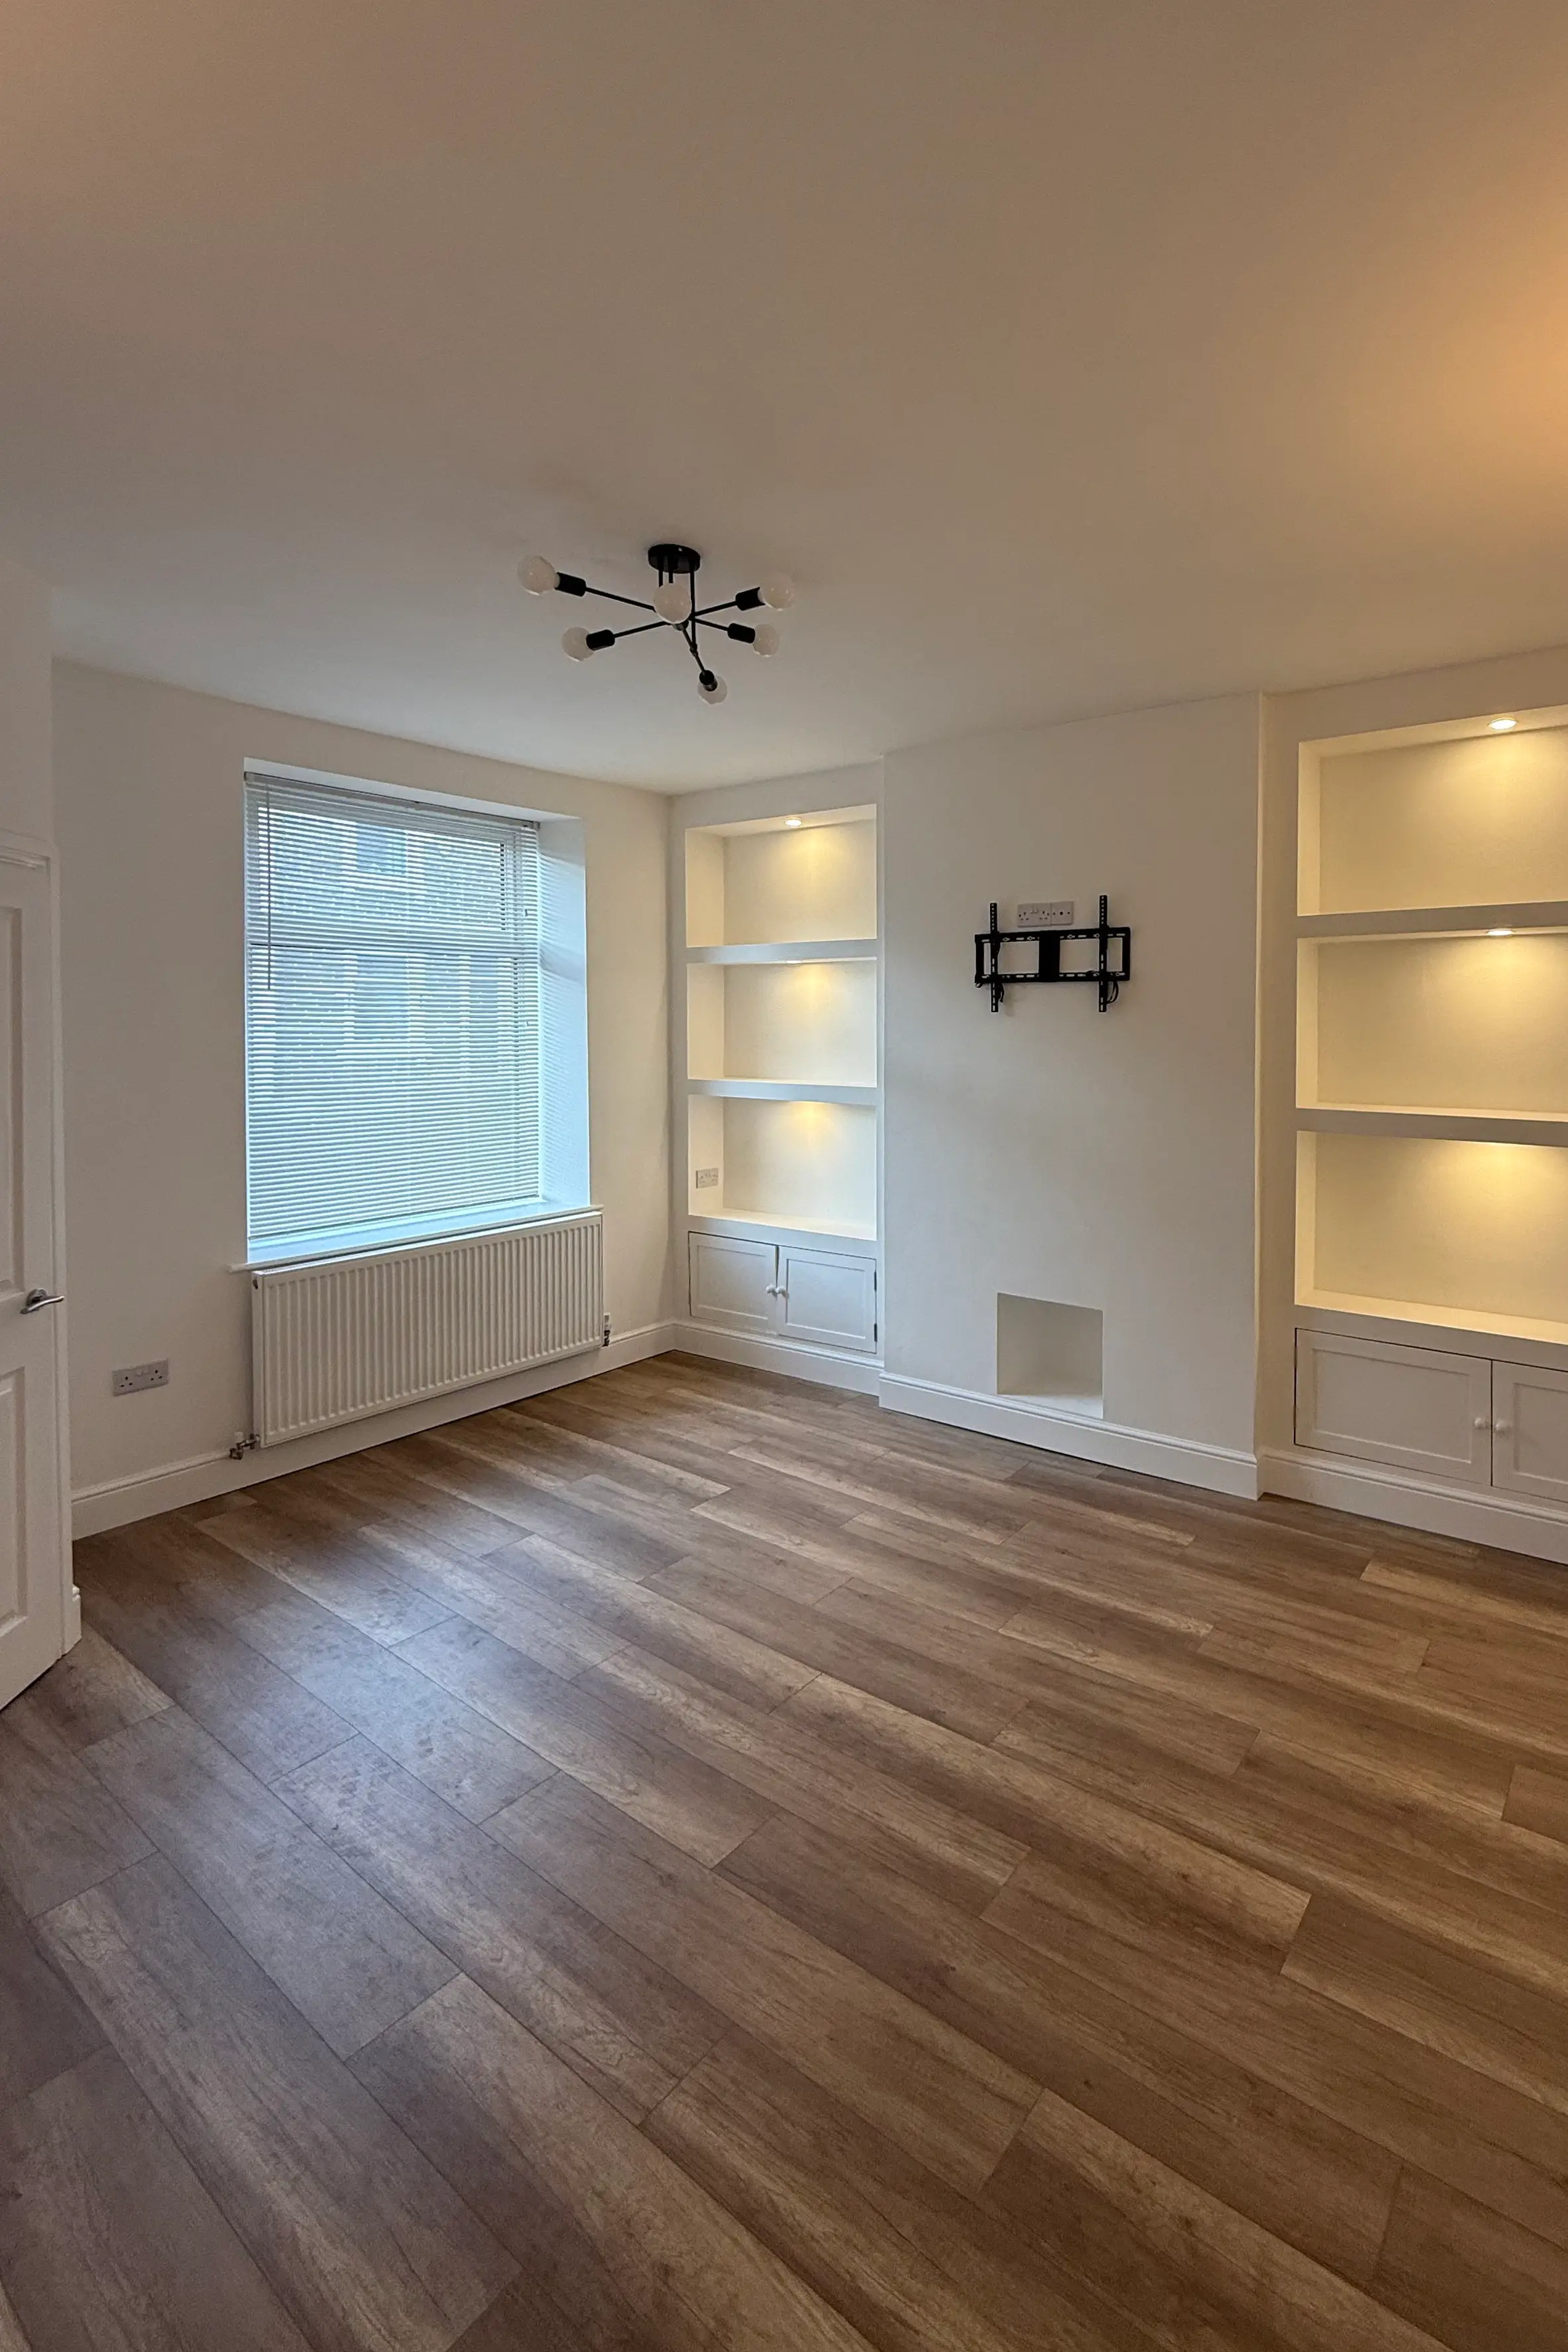
He said: “If someone wants to buy a house, whether to live in or to sell, don’t be afraid to buy something that needs a little work doing to it.
“If you buy something a bit more run-down, you can get much bigger returns on it, as it will have increased in value.”
He shares the progress of his renovation on @buildingwithjacob
 James Holt